The Lab as Fund Manager: Inside the Rise of Self-Directed Corporate Venture Portfolios
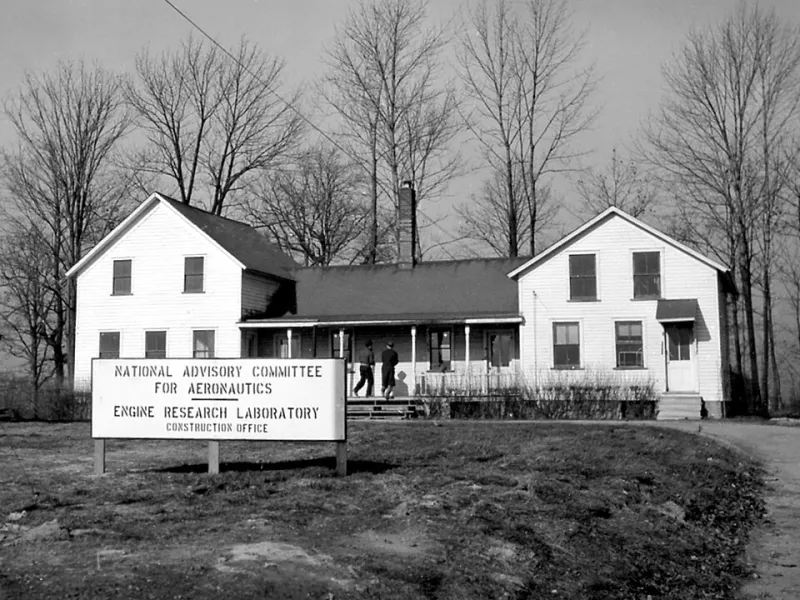
Photo: NASA Glenn Research Center, Public domain, via Wikimedia Commons
For most of the last two decades, the corporate research lab in America followed a familiar script. Engineers explored, managers curated, and a quarterly review decided which experiments graduated onto the product roadmap. The lab was, functionally, a feeder — upstream, subordinate, and perpetually at the mercy of a planning cycle built for incremental releases rather than genuine discovery.
That script is changing. A quiet but growing cohort of US organizations — from logistics operators in Memphis to financial infrastructure firms in Charlotte — has begun running their labs the way a venture fund runs a portfolio. Experiments are funded in tranches. Kill decisions are made early and often. And critically, the lab itself holds the checkbook.
The Portfolio Logic
The core idea is deceptively simple: treat internal prototypes the way a seed investor treats startups. Each project receives a defined funding tranche tied to explicit milestone criteria. At the end of each tranche, the project either raises its next round internally, gets spun into a product, or is shut down with a documented postmortem.
What distinguishes this model from conventional stage-gate processes is who holds the decision rights. In a stage-gate system, the product organization votes on what ships. In the portfolio model, the lab's own leadership — often paired with a finance partner from the CFO's office — makes the call. The roadmap is a customer, not a committee.
Advocates argue this corrects a structural bias. Product roadmaps are optimized for predictability, and predictability systematically starves uncertain-but-potentially-transformative work. A portfolio structure, by contrast, expects a majority of experiments to fail and budgets accordingly. The question shifts from "will this project succeed?" to "is the portfolio's expected value improving?"
Governance Without Gridlock
The obvious objection is accountability. If labs fund themselves, what stops a well-meaning research director from bankrolling a decade of elegant failures?
The companies that have made this work tend to layer three controls on top of the portfolio structure. First, tranche sizes are small and time-boxed — typically 90 to 180 days — so capital exposure per experiment stays modest. Second, an independent review function, often seated in finance or internal audit rather than engineering, validates milestone claims. Third, every kill decision is treated as a deliverable: the postmortem, the reusable artifacts, and the retired infrastructure are catalogued alongside the successes.
One Midwest insurer described its approach as "venture terms with audit-grade paper." Experiments have term sheets. Termination triggers are written down in advance. The lab publishes an internal annual letter, in the style of a fund's LP letter, accounting for every tranche and every shutdown.
Measuring What Matters
Metrics in this model look little like traditional R&D scorecards. Publication counts and patent filings still appear, but the numbers that drive resource allocation tend to be portfolio-level: the ratio of experiments reaching a second tranche, the median time from prototype to first external user, and — perhaps most telling — the cost of a kill decision.
That last metric deserves attention. Organizations that measure the cost of shutting something down, rather than only the cost of running it, discover that cheap exits are a design discipline. Experiments architected to be unwound cleanly — containerized, documented, dependency-light — make the portfolio model viable. Experiments that sprawl make it ruinous.
The Spin-Out Question
The most consequential variation among adopters is what happens when an experiment succeeds. Some organizations route everything back into the product organization, treating the lab as a de-risking engine for the roadmap. Others allow — or encourage — genuine spin-outs: standalone business units with their own P&L, sometimes even external customers.
The spin-out path is where the model earns its venture comparison, and where it generates the most internal friction. Product leaders who watched a lab team "skip the line" to launch a product tend to resist the next funding cycle. Companies navigating this successfully usually formalize the transfer: a defined graduation process, a shared revenue credit, and explicit executive sponsorship for the boundary crossing.
Not a Panacea
The honest caveat is that portfolio-mode labs are expensive by design. They institutionalize failure, and failure carries a morale and political cost that spreadsheets don't capture. Organizations with weak executive cover for the lab leadership should expect the model to erode at the first budget crunch.
Still, the direction of travel is clear. As product cycles compress and the half-life of competitive advantage shortens, the slow conveyor belt from research to roadmap looks increasingly like a liability. A generation of American engineering leaders is concluding that the lab shouldn't just feed the pipeline — it should own the portfolio.